Central banks are not abandoning the financial system—but they are quietly changing what sits underneath it.
When people imagine a major transformation in the monetary system, they often picture a dramatic moment: a currency collapses, markets plunge or banks close their doors.
In reality, significant financial changes rarely arrive with one unmistakable headline. More often, they develop gradually through a series of decisions that appear unremarkable on their own but begin to tell a much larger story when considered together.
That may be what we are witnessing with gold.
Gold’s renewed importance is not evidence that the existing monetary system is about to disappear. It does, however, suggest that some of the institutions responsible for protecting national reserves are becoming less comfortable relying too heavily on any single currency, government or financial asset.
This is not a sudden rejection of the system. It is a gradual rebalancing within it.
A Market Movement Driven by Competing Forces
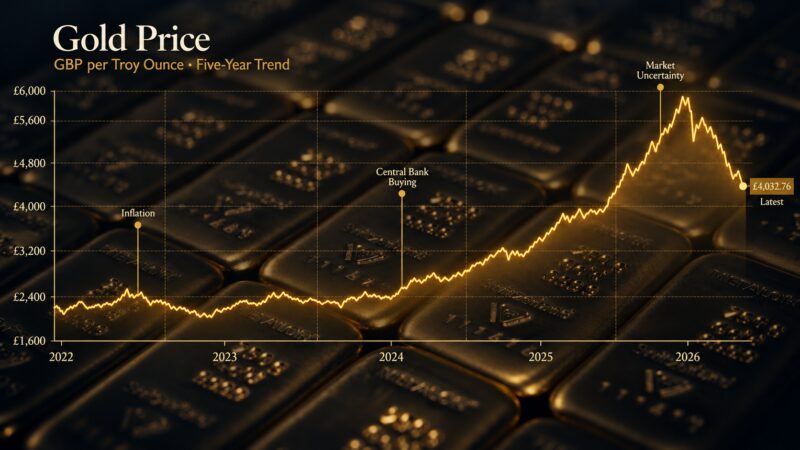
Between the beginning of August and early September 2026, the sterling gold price moved from approximately £2,950 towards £3,250 per troy ounce—a rise of around 10%.
Prices change continuously, so these figures should be understood as a dated market snapshot rather than fixed reference points. Current and historical sterling prices can be viewed through the World Gold Council’s gold-price data.
It would be tempting to explain the rise entirely through geopolitical uncertainty. However, gold rarely responds to only one influence.
On 18 August 2026, for example, gold declined as global bond yields and oil prices rose. Higher energy prices intensified inflation concerns, while rising government-bond yields increased the potential return available from interest-bearing assets. Because gold pays no interest, higher yields can reduce its relative appeal—even during periods of geopolitical tension. Reuters reported that these competing pressures contributed to the decline.
Gold can therefore be pulled in opposing directions:
- Geopolitical and financial uncertainty may support demand.
- Higher interest rates and bond yields may weigh on prices.
- Inflation concerns can strengthen gold’s appeal over the longer term.
- Those same inflation concerns can also lead markets to expect tighter monetary policy.
- Currency movements can alter the price experienced by UK investors.
That is why a single day’s price movement rarely explains the more important story.
The deeper development is taking place within the reserves of some of the world’s largest financial institutions.
Central Banks Continue to Accumulate Gold
According to the World Gold Council’s Gold Demand Trends report, central banks and other official institutions added a net 289 tonnes of gold during the second quarter of 2026.
That represented:
- A fivefold increase from the revised first-quarter estimate of 57 tonnes
- A 62% increase compared with the second quarter of 2025
- The strongest second-quarter total in the World Gold Council’s data series
Poland was the largest reported buyer, adding 51 tonnes during the quarter and taking its official gold holdings to approximately 632 tonnes by the end of June.
China added a further 33 tonnes, bringing its reported holdings to approximately 2,346 tonnes.
Purchases were also reported across Uzbekistan, Kazakhstan, Jordan, the Czech Republic and several other markets. This suggests that official-sector interest was not confined to one country or region.
There is, however, an important balance to include. Total central-bank demand for the first half of 2026 was 345 tonnes—the lowest first-half total since 2022. Selling by countries including Türkiye, Russia and Azerbaijan during the first quarter affected the overall figure.
Central-bank demand remains substantial, but it is neither uniform nor guaranteed. Institutions buy and sell gold according to their own reserve requirements, liquidity needs and economic circumstances.
Why Do Central Banks Hold Gold?
Official reserves help central banks meet external obligations, support confidence, manage currency pressures and provide liquidity during periods of financial stress.
Gold performs a different role from currencies and government bonds because physical gold does not represent somebody else’s financial promise. When held outright, it has no issuing company and carries no issuer-default risk.
This can make it useful as a reserve-diversification asset.
Central banks commonly identify several reasons for holding gold:
- Long-term preservation of value
- Diversification from currencies and government debt
- Performance during periods of geopolitical or financial stress
- High liquidity in established international markets
- The absence of issuer or counterparty risk when held directly
The 2026 Central Bank Gold Reserves Survey found that 89% of participating reserve managers expected global official gold holdings to increase over the following 12 months. A record 45% expected their own institution’s holdings to rise.
The survey also found that 84% expected gold to represent a higher proportion of total reserves within five years.
These are expectations rather than guarantees, but they help explain why gold is increasingly being discussed as a strategic modern reserve asset rather than simply a remnant of an earlier monetary system.
Has Gold Overtaken US Treasuries?
The answer requires careful explanation.
The European Central Bank’s June 2026 review estimated that, at the end of 2025:
- Gold represented approximately 27% of total global official reserves
- US Treasuries represented approximately 22%
- Euro-denominated reserves represented approximately 15%
On that particular measure, the market value of official gold holdings had moved above the value of US Treasury holdings.
This is significant—but it does not mean gold replaced the US dollar as the world’s principal reserve currency.
US Treasuries are only one form of dollar-denominated reserve asset. The dollar remained the dominant currency within global foreign-exchange reserves, accounting for approximately 57% of disclosed currency reserves in 2025.
It is also essential to understand the effect of price appreciation.
The ECB explained that much of gold’s increased share resulted from the substantial rise in its market price during 2024 and 2025. As gold became more valuable, the reported weight of existing holdings increased—even without an equivalent quantity of new metal being purchased.
When the ECB recalculated the comparison using gold’s price at the end of 2023, gold represented approximately 16% of reserves, equal to the euro, while US Treasuries represented approximately 26%.
The figures therefore reveal two developments taking place simultaneously:
- Central banks have continued adding physical gold.
- Rising prices have increased the value and proportional importance of gold already held.
Both matter, but they should not be confused.
Not a Collapse—A Gradual Rebalancing
The evidence does not suggest that central banks are collectively abandoning currencies, government debt or the established financial system.
A more credible interpretation is that reserve structures are becoming increasingly diversified.
Central banks can continue holding dollars, euros and government bonds while also increasing their exposure to gold. These positions are not contradictory.
Different reserve assets perform different functions:
- Currencies provide liquidity for trade, intervention and international payments.
- Government bonds can generate income and serve as highly liquid financial assets.
- Gold offers diversification and does not depend on the solvency of an issuing institution.
Gold also has limitations. It produces no interest, its price can be volatile and physical holdings involve secure transportation, insurance and storage costs. Its supply cannot expand quickly when demand for international liquidity changes.
For these reasons, gold is unlikely to replace major reserve currencies. Its growing role is better understood as an additional layer of resilience within the system.
What Can Private Investors Learn From This?
Private buyers should be careful not to imitate central-bank decisions without considering the enormous differences in objectives, resources and time horizons.
A central bank manages national reserves. A private investor manages personal wealth.
Nevertheless, the underlying principle of diversification may still be relevant.
The lesson is not that everybody should move their savings into gold. It is that sophisticated institutions are reconsidering how much reliance they place on individual currencies, debt markets and political systems.
Anyone considering physical bullion should think carefully about:
- The purpose of the purchase
- The intended holding period
- How bullion fits within their wider financial position
- Product premiums above the underlying metal price
- Secure storage and insurance
- The process and cost of selling in the future
- Their ability to tolerate short-term price declines
Central-bank demand may support the longer-term case for gold, but it does not guarantee rising prices. Gold can experience substantial corrections even when the broader strategic argument remains intact.
The Development Worth Watching
Perhaps the most useful question is not:
“When will the monetary system collapse?”
A more measured question is:
“Why are the institutions responsible for protecting national reserves increasing the strategic role of gold?”
The answer appears to involve diversification, geopolitical risk, long-term value preservation and a desire to reduce dependence on any single financial asset.
This is not the dramatic replacement of one monetary system with another.
It is quieter, more gradual and potentially more important: a change in the foundations beneath the existing system.
Considering Physical Gold or Silver?
Whether you are making your first bullion purchase or adding to an established holding, KNIGHTS Bullion offers competitive, market-led pricing supported by knowledgeable and personal service.
Our team can explain the practical differences between coins and bars, current premiums, secure storage, insured delivery and future resale options—allowing you to make an informed decision without pressure.
Begin with a private conversation with the KNIGHTS Bullion team.
This article is provided for general information only and does not constitute personal financial, investment, legal or tax advice. Physical bullion is not an FCA-regulated investment. Precious-metal prices can fall as well as rise, and past performance does not guarantee future results. Consider your circumstances and seek independent professional advice where appropriate.